Florida Contractor Insurance
Insurance that keeps contractors working.
MAD Insurance helps contractors and skilled trades compare the coverage they need for job sites, employees, vehicles, tools, contracts, and completed work—with guidance from an independent Florida agency.
Built around the work you perform
Contractors and trades we help insure
Insurance eligibility and pricing depend on the exact operations, project types, payroll, subcontractor costs, experience, and safety controls. Tell us everything your business does so we can approach the right markets.
Coverage built around your jobs
Most contractors need a coordinated group of policies. We help identify the gaps between your operations, vehicles, people, equipment, and contract requirements.
General Liability
Protection for eligible third-party bodily injury, property damage, and completed-operations claims.
Explore general liability →Workers’ Compensation
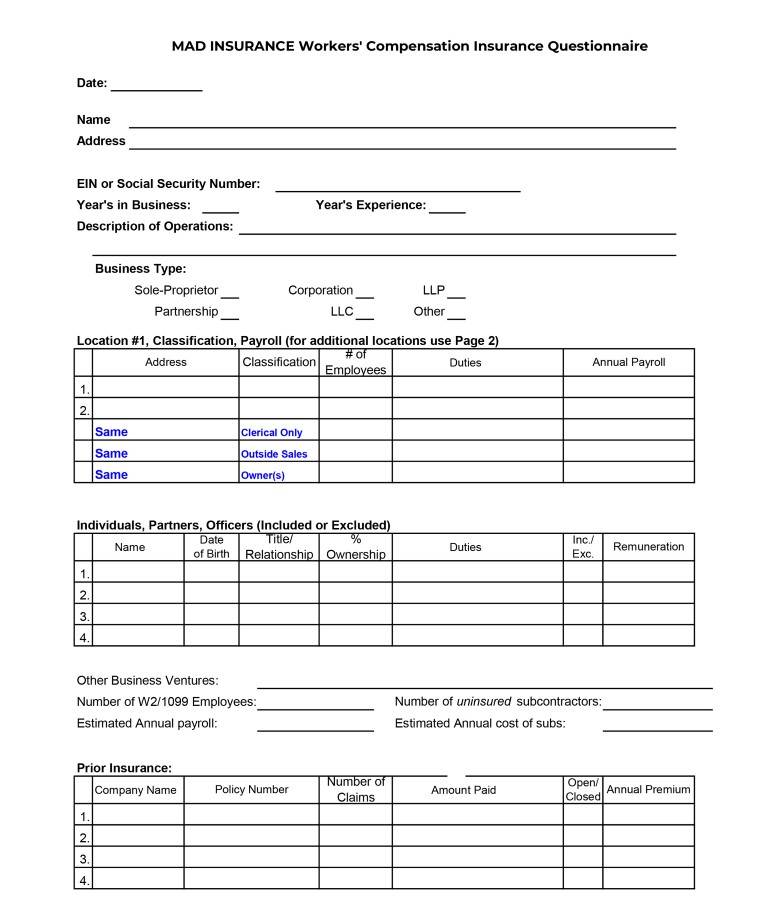
Coverage for eligible employee injuries and occupational illnesses, subject to policy terms and applicable requirements.
Explore workers’ compensation →Commercial Auto
Coverage for owned, leased, or hired vehicles used to carry workers, tools, materials, and equipment.
Explore commercial auto →Tools & Equipment
Inland marine options for mobile tools and scheduled equipment in storage, transit, or at job sites.
Discuss tools and equipment →Builders Risk
Property coverage designed for eligible buildings and projects while construction or renovation is underway.
Explore builders risk →Umbrella & Excess
Additional liability limits above eligible underlying policies for contracts and severe losses.
Explore commercial umbrella →Professional Liability
Important when your business provides design, consulting, specifications, or other professional services.
Explore professional liability →Commercial Property
Coverage options for shops, offices, warehouses, business contents, and qualifying income exposures.
Explore commercial property →Cyber & Crime
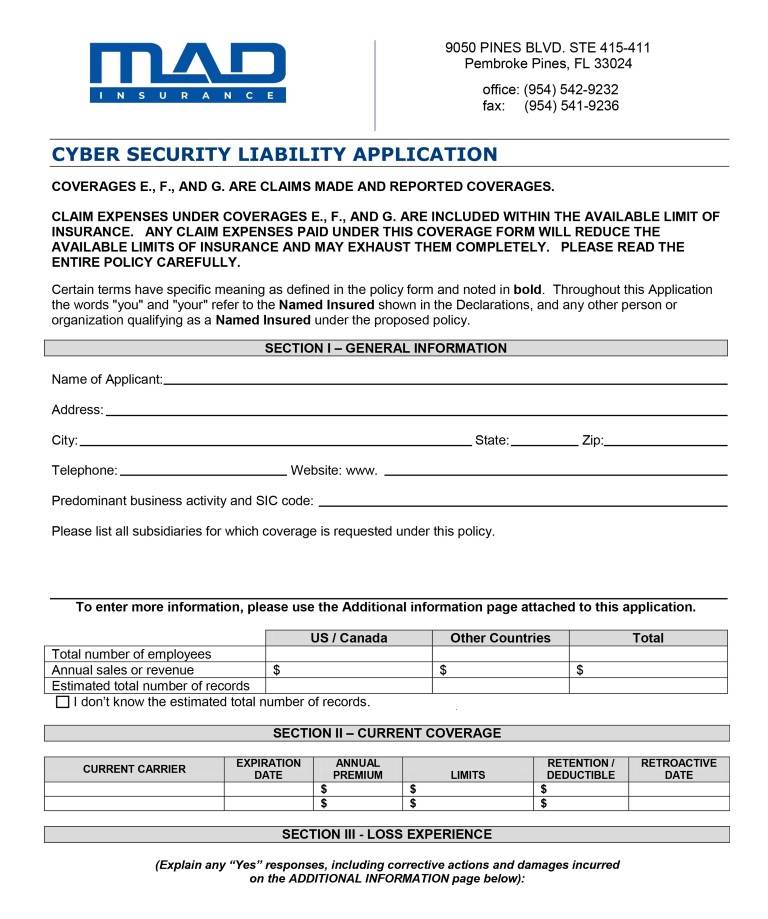
Options addressing data incidents, fraudulent transfers, ransomware, and certain technology-related losses.
Explore cyber liability →Before you sign the contract
Insurance requirements can change the job.
Send us the insurance section of your contract before work begins. We can compare its requirements with the policies in force and explain what may require an endorsement, higher limit, or separate policy.
Send us your insurance documents
Skip the questionnaire. Add a quick note, then drag and drop your policies, loss runs, declaration pages, contracts, certificates, or schedules below.
Start Guided Contractor Quote
What we need to quote accurately
Better information helps us select appropriate carrier options and reduces delays, audit surprises, and requests for follow-up documentation.
Operations and projects
Exact trade, all work performed, residential versus commercial mix, maximum project size, territories, heights, excavation, roofing, hot work, and other specialized operations.
People and subcontractors
Payroll by job duty, employee count, subcontractor costs, certificates collected, years of experience, licensing, and loss history.
Vehicles and equipment
Drivers, vehicles, trailers, mobile tools, heavy equipment, storage, radius of operation, and current policy information.
Choose the fastest way to start
The guided form includes an optional upload step for current policies, loss runs, contracts, certificates, vehicle schedules, and equipment lists.
Recommended
Start the guided contractor quote
Answer one question at a time. The form covers operations, revenue, payroll, subcontractors, vehicles, tools, bonds, claims, and supporting documents.
Start Guided QuotePrefer a PDF?
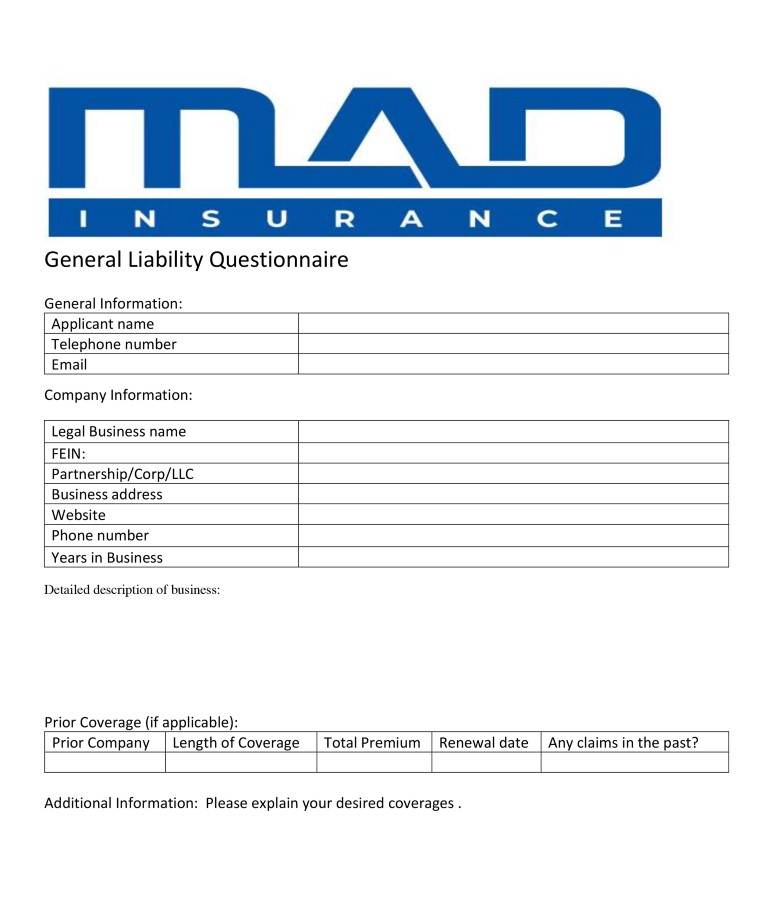
Download the fillable contractor general-liability questionnaire, save it, and email the completed file to our team.
Open contractor PDF →Need another GL form?
Access forms for habitational, professional-service, and retail risks from our General Liability page.
View all GL questionnaires →Contractor insurance questions
Can one policy cover every contractor exposure?
Usually not. General liability, workers’ compensation, commercial auto, tools and equipment, builders risk, professional services, bonds, and excess liability may require separate policies or endorsements.
Do subcontractors need their own insurance?
Many carriers and contracts expect subcontractors to maintain appropriate insurance and provide certificates. The exact requirements vary, so your subcontractor process should be reviewed with your insurance and legal advisors.
Does general liability cover stolen tools?
General liability generally addresses eligible third-party claims, not theft of your own tools. Tools and equipment are commonly insured through inland marine or contractor equipment coverage.
Can MAD Insurance help with certificates?
Yes. Existing clients can submit certificate requests online. A certificate reflects the policies actually in force; endorsements or contract changes may require additional review.
Why does my exact trade description matter?
Insurance carriers classify and price businesses according to their actual work. Disclosing all operations—including subcontracted and occasional work—helps avoid incorrect classification and potential coverage problems.
Can I upload my current policy and loss runs?
Yes. The guided contractor form includes an optional supporting-document upload field near the end. You can attach current policies, loss runs, contracts, certificates, schedules, and related records.
Local guidance from two Florida offices
MAD Insurance serves contractors throughout Florida, with teams available from our Pembroke Pines and Stuart offices.
Pembroke Pines
9050 Pines Blvd, Suite 355
Pembroke Pines, FL 33024
Coverage, eligibility, classifications, limits, exclusions, deductibles, and availability vary by carrier and policy. This page is general information and does not modify or guarantee insurance coverage. Contract language should also be reviewed by qualified legal counsel.