Protect the work and advice your clients rely on.
Explore coverage for professional mistakes, alleged negligence and claims tied to the services you provide.
Get started
What kind of professional work do you do?
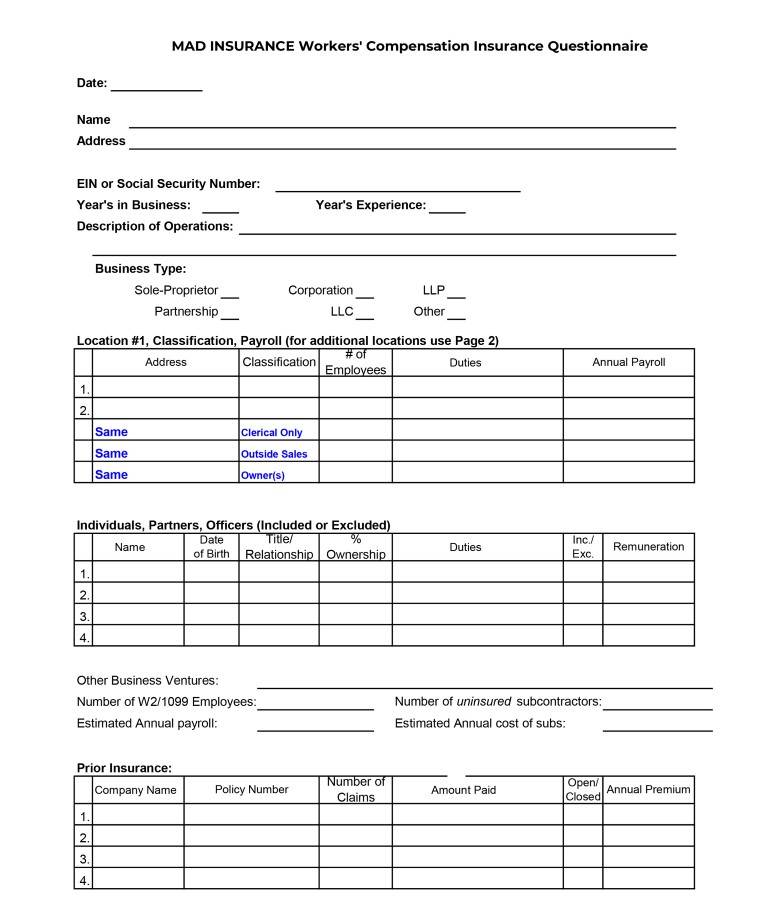
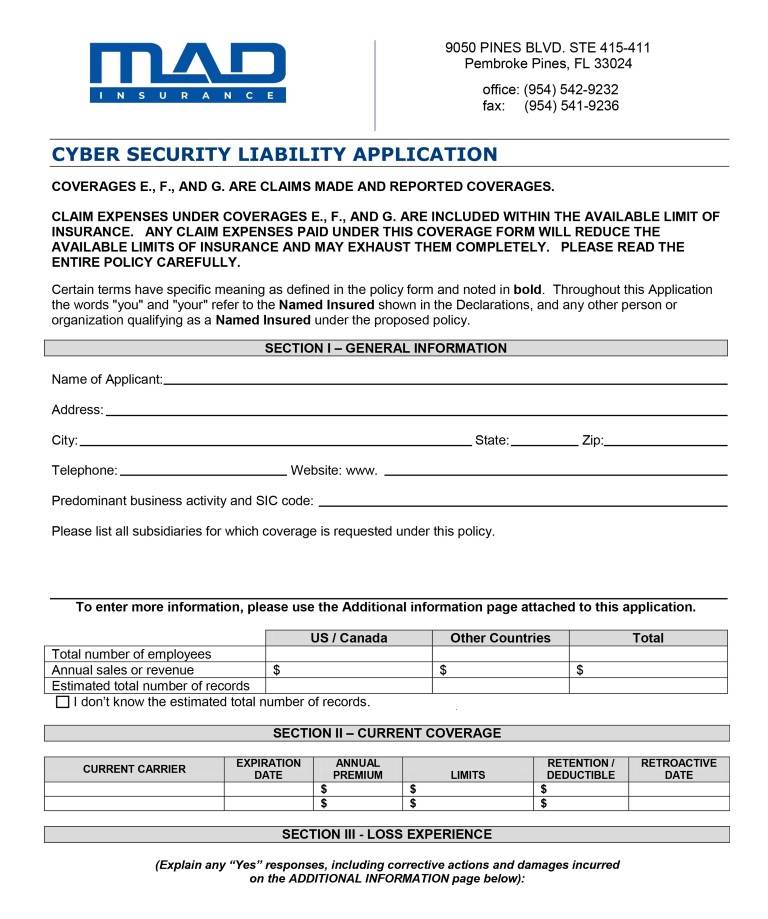
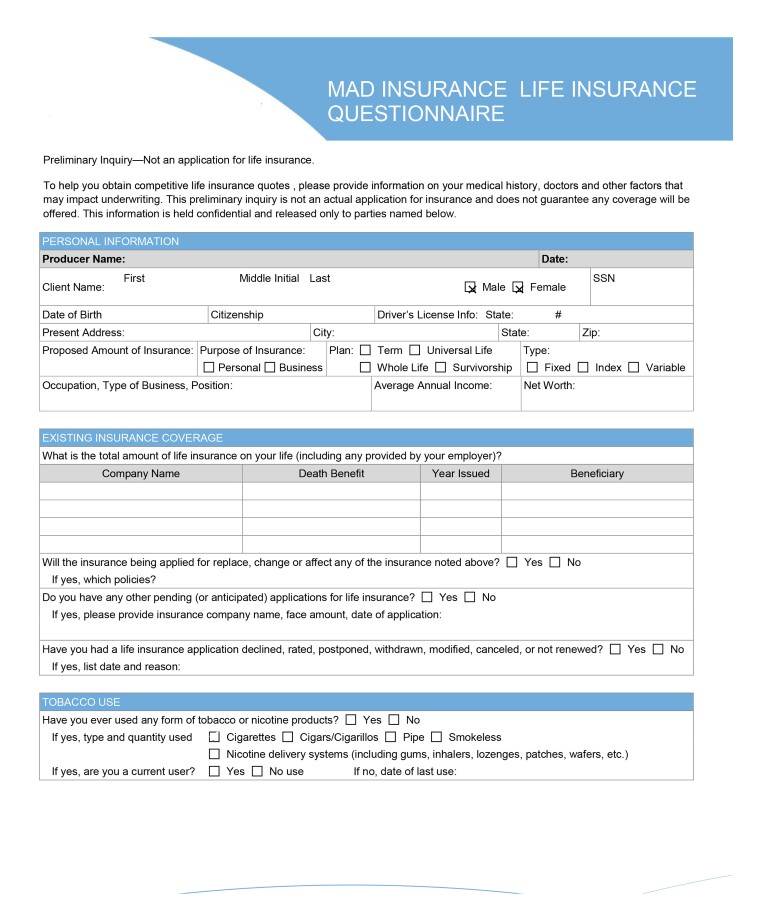
Choose a questionnaire for your specialty, or use the general online form. For a PDF, complete and save it, then email it to [email protected].
General Online Application
A guided option if your practice does not match a specialty questionnaire.
Complete Online FormNurse Practitioner
For individual NPs and NP-owned practices.
Open NP QuestionnaireRegistered Nurse
For individual RNs and their clinical duties.
Open RN QuestionnaireMed Spa Package
Professional liability, general liability and commercial property in one questionnaire.
Open Med Spa PackageExplore Med Spa InsuranceErrors & Omissions
For consultants and service firms whose advice or errors may cause financial loss.
Open E&O QuestionnaireMedical Malpractice
For physicians, clinics and healthcare organizations.
Open Medical QuestionnaireDirectors & Officers
For private companies and nonprofits seeking management liability coverage.
Open D&O QuestionnaireLawyers Professional Liability
For law firms and attorneys, including practice and risk control questions.
Open Lawyers QuestionnaireTechnology E&O
For software, SaaS, IT consulting, managed services and cloud providers.
Open Technology QuestionnaireArchitects, Engineers & Design-Build
For design professionals and firms, including contracts and project mix.
Open A&E QuestionnaireUse the general online form and our team can route your request.
Coverage overview
Protection for professional services
Professional liability can respond to eligible claims that your work, advice or care caused a client financial harm or injury. The details depend on your profession and policy.
Common questions
Professional liability FAQs
Is professional liability the same as general liability?
No. General liability generally addresses covered third-party bodily injury and property damage. Professional liability focuses on eligible claims arising from professional services, advice or care.
What is the difference between claims-made and occurrence-based professional liability?
A claims-made policy generally responds when a claim is first made against you during the policy period and reported as the policy requires, as long as the alleged professional service took place on or after the policy’s retroactive date. You usually need to keep continuous coverage or arrange an extended reporting period (sometimes called “tail” coverage) when the policy ends or changes, so later claims about earlier work can still be reported.
An occurrence policy generally responds based on when the covered professional service or event occurred: if the policy was in force then, it may respond even if the claim is made later, subject to the policy’s terms. For example, if work was performed in 2025 and a claim is made in 2027, a claims-made policy would generally need to be in force when the claim is made with a retroactive date that reaches back to the 2025 work; an occurrence policy would generally look to the policy in force when the work occurred.
Claims-made coverage is more common for professional liability, while occurrence availability varies by profession and insurer. The policy wording controls, so ask a licensed agent to review the retroactive date, reporting requirements and any tail coverage before changing or ending coverage.
Do I need a specialty questionnaire?
If your profession appears above, choose that questionnaire so we can collect the details relevant to your work. Otherwise, use the general online form.
When does coverage begin?
Submitting a questionnaire does not bind coverage. A licensed MAD Insurance agent must confirm the terms and effective date.
Prefer to complete it online?
General Professional Liability Application
Submit your information to our team through the form below.