Everyday drives.
Extraordinary care.
Florida auto insurance for the car you drive and the life you’re building. Compare available options with a licensed MAD Insurance advisor—from daily drivers to luxury and collector vehicles.
Prefer a conversation? Call 954-541-9232.

What does your everyday drive look like?
Choose a vehicle type for a few practical points to discuss with your advisor.
A policy for the miles you actually drive.
Bring your current policy, annual mileage, garaging address, and every household driver. We can review liability limits, deductibles, rental reimbursement, and opportunities to bundle.
Some cars call for a more specialized conversation.
For a special car, look beyond a standard quote. Discuss valuation, driving frequency, garaging, repair provisions, modifications, and how the rest of your household is insured.
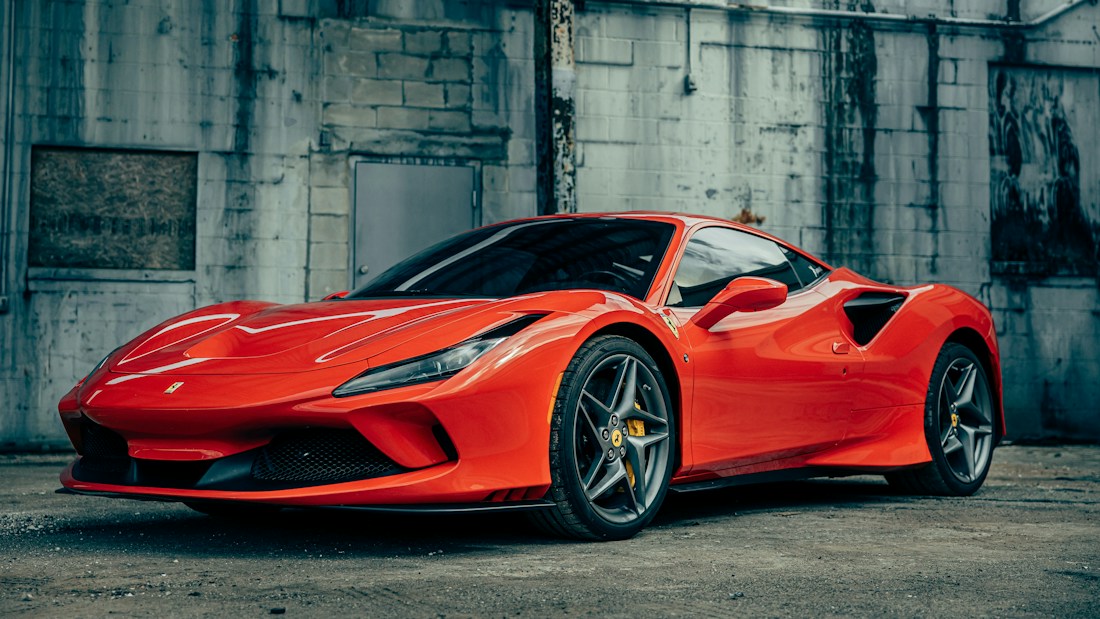 Ferrari F8 Tributo ↗
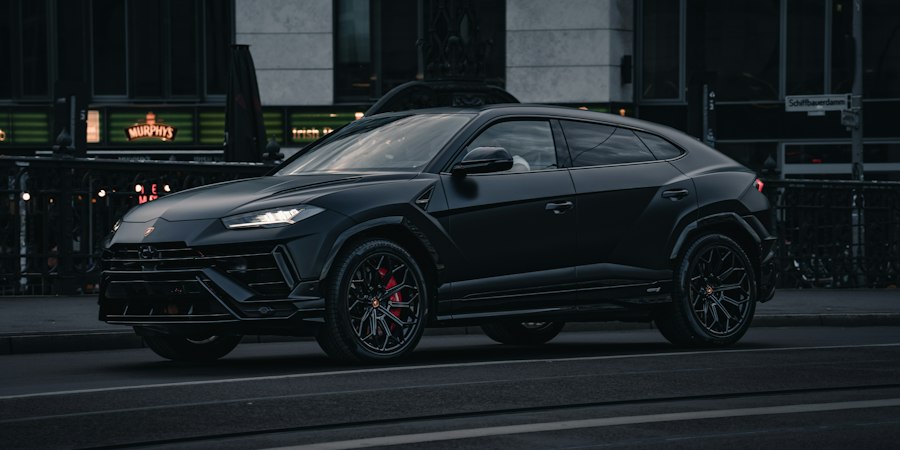
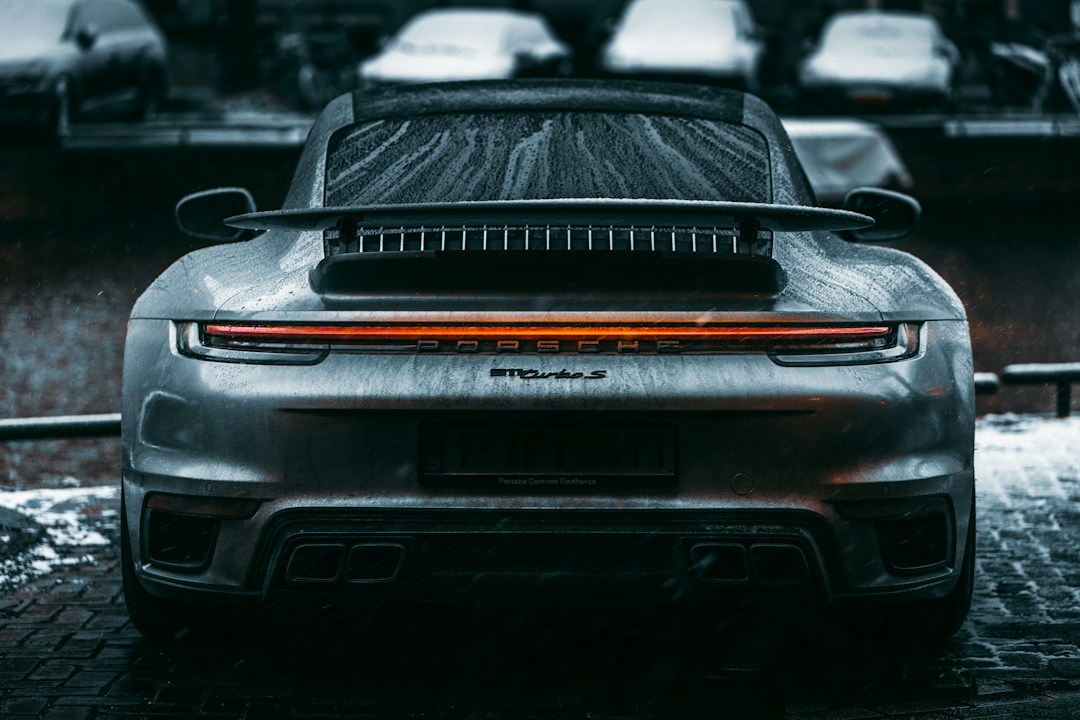
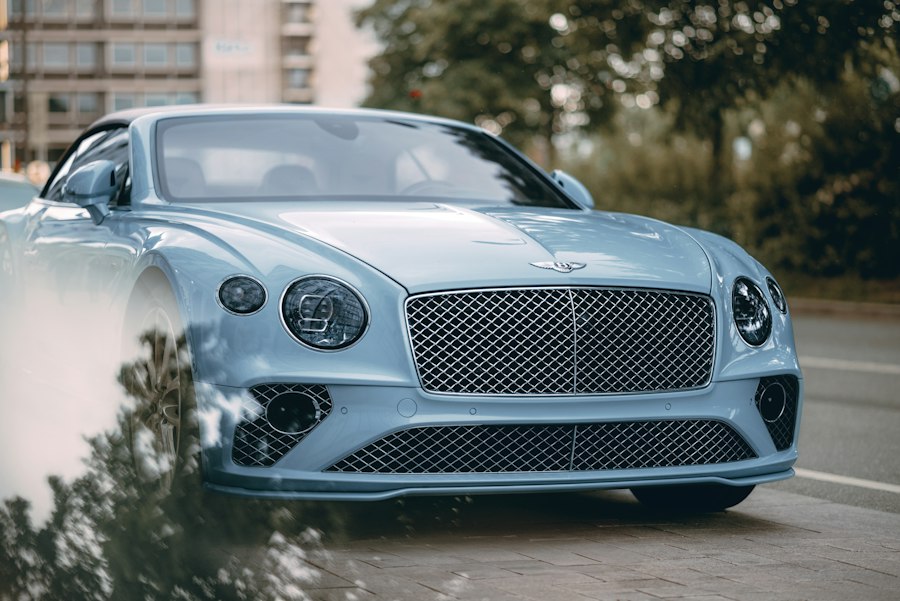
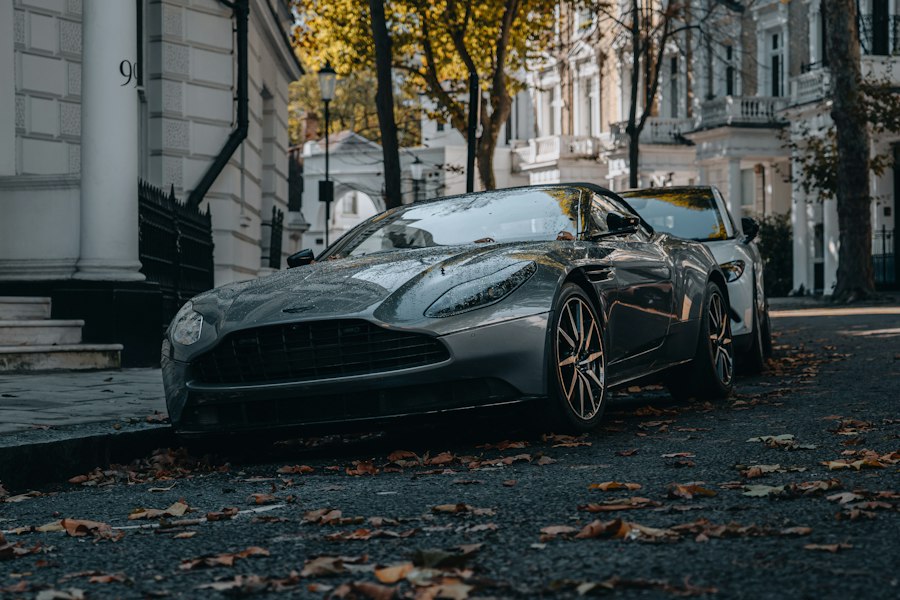
Select a photo to enlarge it. Vehicles shown illustrate the types of cars to discuss with MAD; acceptance, valuation, and coverage depend on the insurer, vehicle, driver, and use.
Driving for Uber, Lyft, or a black car service?
Uber & Lyft in your personal vehicle
Some carriers offer a rideshare endorsement on an eligible personal auto policy. Tell us how you drive so we can review available options and coverage while you are offline, waiting for a request, and on a trip.
Uber Black, Black SUV & limo drivers
Professional black car and limousine operations need a commercial auto / livery coverage review. Share your vehicle, drivers, service area, and platform or permit requirements with our team.

More places to look.
One team to guide you.
Explore MAD’s auto-market roster. We review available options based on your vehicles, drivers, household, and underwriting eligibility.

Progressive

GEICO

National General

Bristol West

Kemper Auto / Infinity

Ocean Harbor / Pearl Holding

United Automobile

Travelers

Responsive Auto

Embark General

Nationwide

Amwins Specialty Auto
Root Insurance
Hagerty
Showing all 14 auto markets.
Logos identify carrier or program relationships; they do not mean every company is available for every risk. Availability, products, discounts, and eligibility vary. View MAD’s full carrier directory →
Know what each part of your policy does.
Choose a coverage to see what it addresses, an example, and a useful question for your advisor.
Bodily injury liability
Helps with covered injury claims when you are legally responsible for injuring someone else.
An at-fault crash causes another driver’s injuries.
Review per-person and per-accident limits, then ask whether umbrella coverage fits your household.
Examples are illustrative and do not guarantee coverage. Actual limits, deductibles, exclusions, and policy wording control.
Start with the requirements.
Then consider your real exposure.
For most Florida-registered private passenger vehicles, basic registration requirements include PIP and property damage liability. Those limits are a starting point for a coverage conversation.
Generally required personal injury protection (PIP) limit.
Generally required property damage liability (PDL) limit.
Liability, uninsured motorist, physical damage, and your out-of-pocket exposure together.
Requirements can differ by vehicle, driver, or financial-responsibility situation. See FLHSMV insurance guidance. Ask MAD to review what applies to you.
Find savings that still fit your life.
We can review available discounts and policy choices without treating the lowest premium as the only goal.
Ask us to check
- Home, condo, or renters bundling
- Paid-in-full and automatic-payment options
- Good-student and driver-training discounts
- Eligible safety and anti-theft features
- Telematics programs and their terms
- Deductibles you could afford after a loss
Bring the full picture
Have household driver and license information, vehicle VINs, garaging addresses, mileage, and your current declarations ready.
Tell us about teen drivers, delivery or rideshare work, business use, custom equipment, and vehicles kept at another address.
Discounts and program availability vary by insurer and eligibility.
Three steps to a more informed quote.
1. Share your household
List drivers, vehicles, use, and current coverage accurately.
2. Review the tradeoffs
Compare limits, deductibles, policy features, and available markets.
3. Confirm the details
Review effective dates and required documents before making a change. Avoid a gap in coverage.
Useful answers before you choose.
Does “full coverage” mean everything is covered?
Should I review uninsured-motorist coverage?
When should I get a quote for a new car?
Can you review a luxury or exotic vehicle?
What if I drive for Uber, Lyft, or deliveries?
Can I bundle my home or renters policy?
Let’s build your auto quote.
Start online or complete the PDF questionnaire. Our team can help review available options for your household.
Start online
Use MAD’s online quote request to share your driver, vehicle, and coverage information.
Use the fillable PDF
Download the personal auto questionnaire, complete and save it, then email it to [email protected].
Want help first? Call 954-541-9232 or email MAD Insurance.