Florida Healthcare Business Insurance
Insurance for med spas and healthcare professionals.
MAD Insurance helps medical aesthetics businesses, wellness practices, and healthcare professionals compare coverage for professional services, patients, property, employees, technology, and products.
Coverage shaped around your services
Healthcare businesses and professionals we help
Carrier appetite depends on the services performed, provider credentials, supervision, patient population, equipment, products, protocols, claims history, and business structure. We help present those details clearly.
Coverage for the full practice—not only malpractice
Professional liability is central, but a healthcare business may also need protection for premises, employees, patient information, equipment, products, and business interruption.
Professional Liability
Coverage for eligible claims alleging errors, omissions, or harm arising from covered professional healthcare services.
Explore professional liability →General Liability
Protection for eligible third-party bodily injury, property damage, and premises-related claims.
Explore general liability →Property & Business Income
Options for tenant improvements, furniture, supplies, qualifying equipment, and certain covered interruptions.
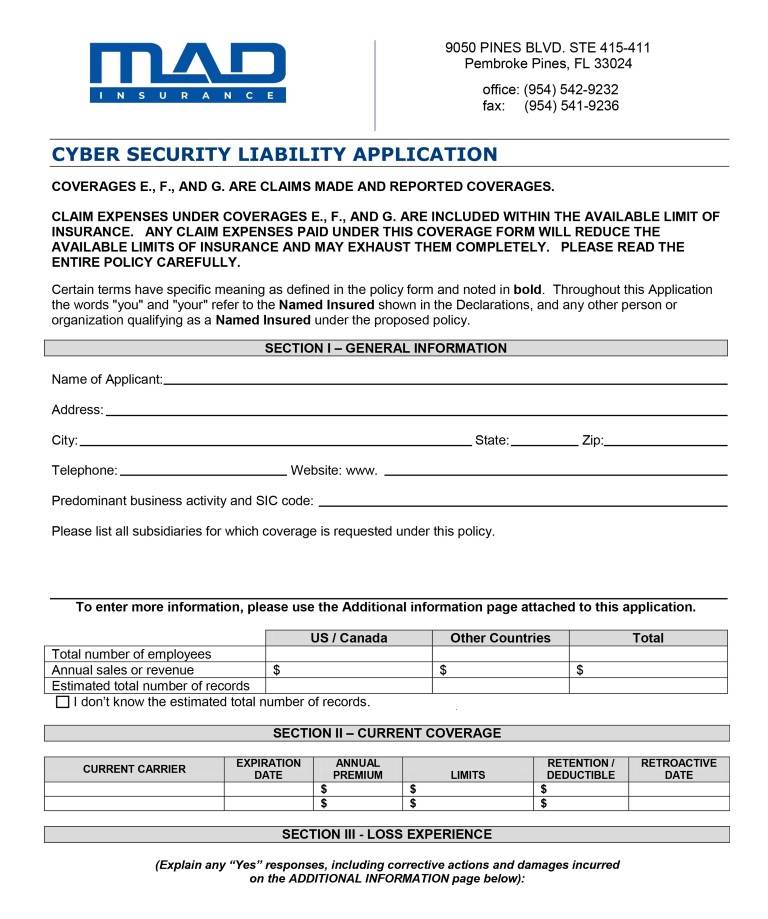
Explore commercial property →Cyber Liability
Protection options for patient-data incidents, ransomware, notification costs, system interruption, and cybercrime.
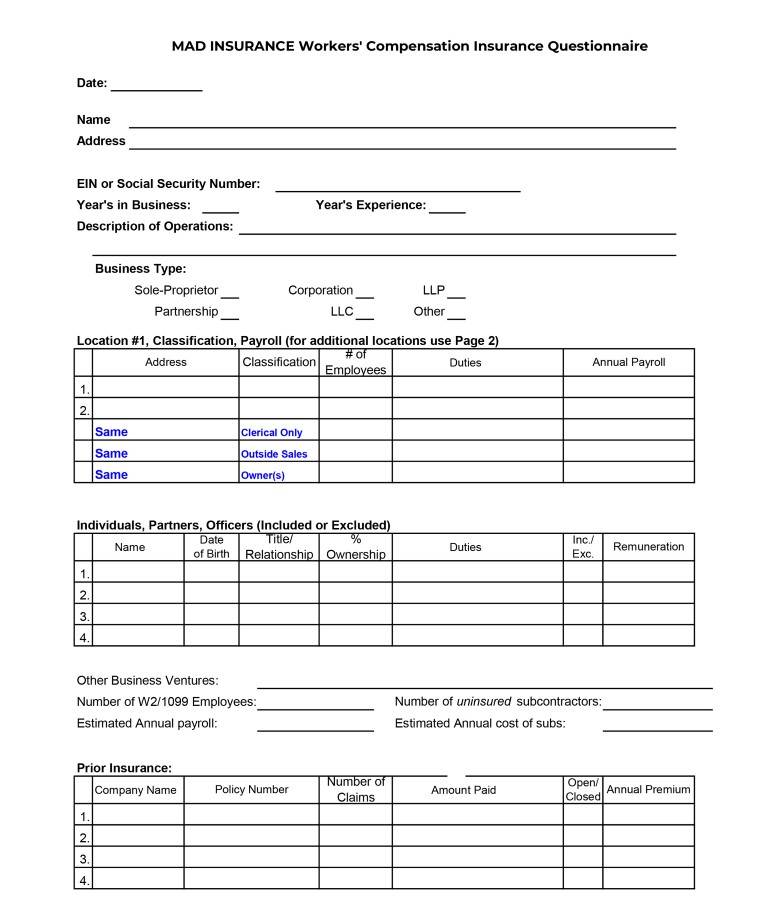
Explore cyber liability →Workers’ Compensation
Coverage for eligible employee injuries and occupational illnesses, subject to policy terms and applicable requirements.
Explore workers’ compensation →Products Liability
Important when the practice sells, dispenses, private-labels, or recommends supplements, skincare, or wellness products.
Discuss products coverage →Employment Practices
Options addressing eligible allegations such as discrimination, harassment, retaliation, and wrongful termination.
Discuss employment practices →Equipment Breakdown
Coverage options for eligible mechanical or electrical breakdown involving insured diagnostic, treatment, and business equipment.
Discuss equipment protection →Umbrella & Excess
Additional liability limits above eligible underlying policies when contracts or severe losses require more protection.
Explore commercial umbrella →Why the details matter
One med spa can have several distinct exposures.
Ownership, the medical director relationship, provider credentials, procedures, treatment locations, equipment, products, consent practices, and patient records can all affect eligibility and coverage structure.
Services and exposures carriers may review
This is not an eligibility list. It helps applicants recognize the level of detail carriers may require before offering terms.
Choose the right application path
Start online or use an industry-specific fillable PDF. The guided application includes an optional upload field for current policies, loss runs, contracts, provider schedules, and supporting records.
General healthcare and professional services
Guided professional-liability application
Use the conversational form when you want to answer one question at a time and attach supporting documents at the end.
Start Guided ApplicationHealthcare insurance questions
Is professional liability the same as general liability?
No. Professional liability generally addresses eligible allegations arising from covered professional services. General liability typically addresses eligible premises and other third-party bodily injury or property-damage claims. Many healthcare businesses should review both.
Does a med spa need coverage for every provider?
The application should identify every provider and their relationship to the business. Whether a provider is scheduled, separately insured, employed, or contracted depends on the carrier, policy structure, and facts of the practice.
Can one policy cover professional liability, property, and general liability?
Some programs may package multiple coverages, while others require separate policies. We review how the policies coordinate and identify important gaps or separate requirements.
Why are procedures and devices important?
Different services and devices create different clinical and underwriting exposures. Accurate disclosure helps us approach carriers whose appetite aligns with the actual practice.
Can I upload current policies and loss runs?
Yes. The guided application includes an optional supporting-document upload field. You can include policies, loss runs, contracts, provider schedules, equipment lists, and related records.
Does MAD Insurance provide legal or clinical compliance advice?
No. We help evaluate insurance needs and policy options. Licensing, ownership, supervision, privacy, consent, and clinical requirements should be reviewed with qualified legal and healthcare-compliance professionals.
Independent guidance from two Florida offices
MAD Insurance serves healthcare professionals and businesses throughout Florida, with teams available from Pembroke Pines and Stuart.
Pembroke Pines
9050 Pines Blvd, Suite 355
Pembroke Pines, FL 33024
Coverage, eligibility, classifications, limits, exclusions, deductibles, and availability vary by carrier and policy. This page is general information and does not modify or guarantee insurance coverage. Medical, legal, licensing, and compliance matters should be reviewed with appropriately qualified professionals.